Duration
About 3.5 hours
You set every stage timing from the professor panel, so it fits one block or splits across two sessions.
Corporate Tax Strategy Simulation
The Finsimco Corporate Tax Strategy Simulation gives each student a multinational's tax function and a statutory rate to work down from. Six levers behave very differently, and an audit arrives two years later to ask what stands behind each one.
Duration
You set every stage timing from the professor panel, so it fits one block or splits across two sessions.
Format
Each student holds the planning, substance and reporting roles in turn and submits one tax position.
Level
Adjustable: two domestic levers on a given rate, up to transfer pricing, deferred tax and an audit with penalties.
Professor tools
Manage students, adjust stage timings, control progression and monitor individual inputs.
Prerequisites
Students need to read an income statement. Effective and cash rates and transfer pricing are taught inside.
Delivery
The web-based simulation supports in-person, remote, blended and homework-supported delivery.
Assessment
Every submission is individual, so the structure, the substance file and the review answers export per student.
Course fit
Designed for Corporate Tax, Taxation, International Business, Accounting and Corporate Finance courses.
The topics a corporate tax strategy module has to cover: the effective tax rate reconciliation, permanent against timing differences, deferred tax and the valuation allowance, transfer pricing and the arm's length principle, substance behind a foreign rate differential and the effective rate against cash taxes paid.
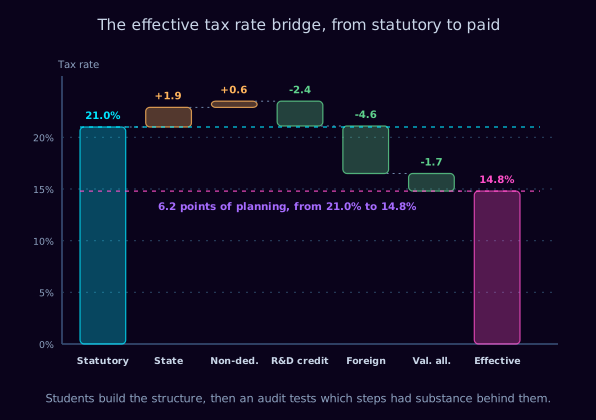
This bridge is the most useful figure in corporate tax, and students read it as a set of reductions rather than a set of commitments. Each step has a different character. A research credit is permanent and cheap to defend. State taxes are a cost of being where the business is. A foreign rate differential is the largest step and the one that needs real activity in the jurisdiction claiming it. A released valuation allowance lowers the reported rate and changes no cash at all.
Written to drop into your module descriptor without rewriting. On completing the simulation, your students will be able to:
Each student runs the tax function alone, holding the planning, substance and reporting roles in turn. All three want something different from the same structure, and only one position is signed.
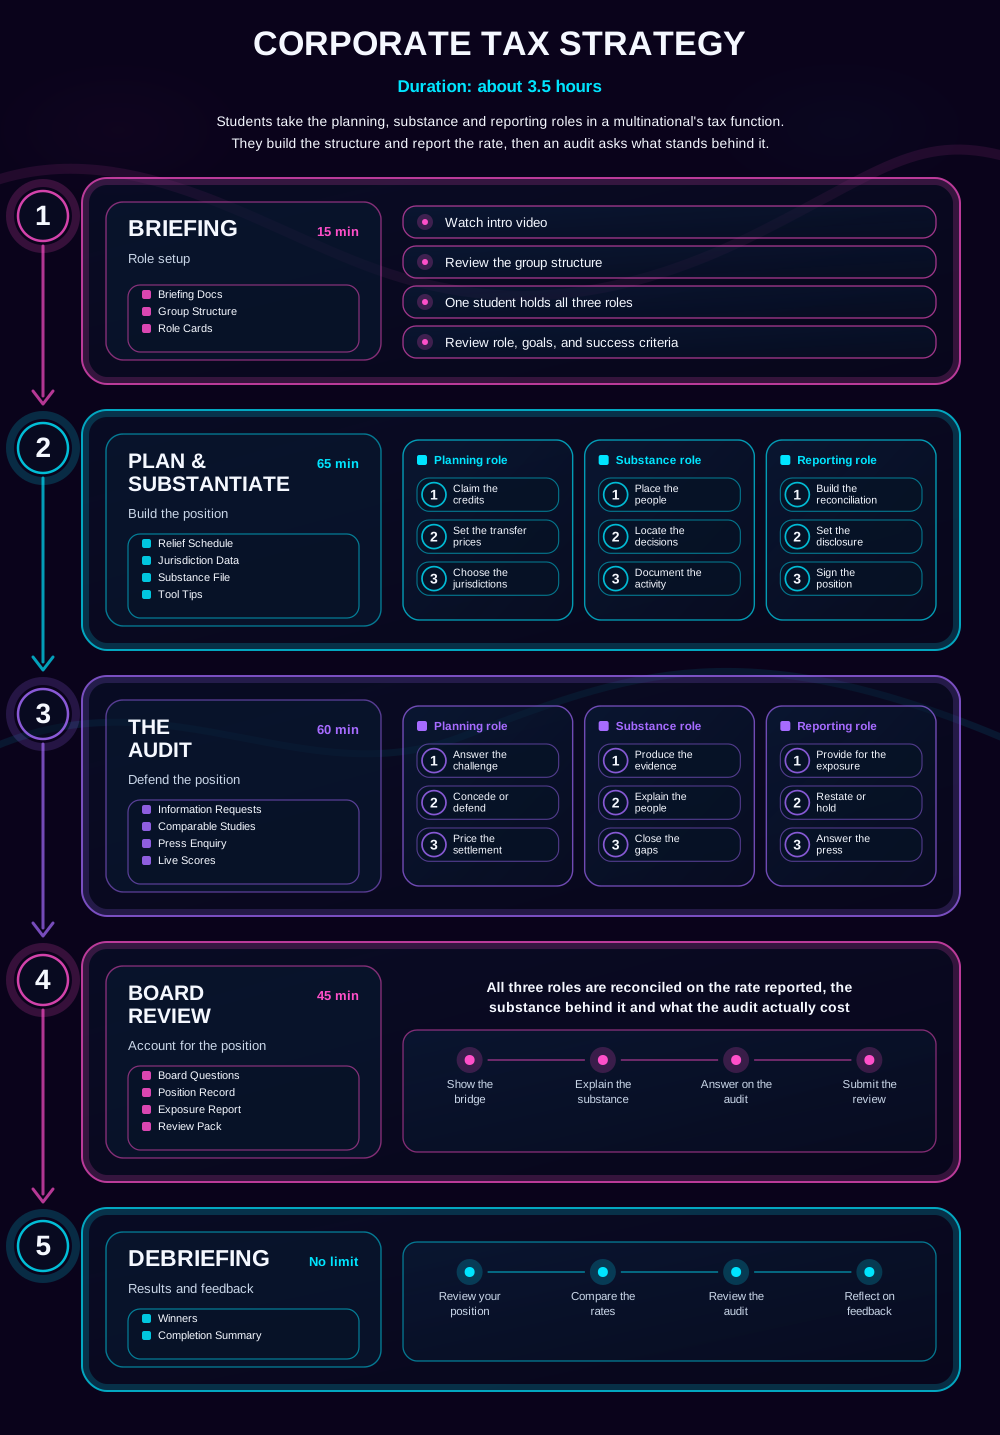
The gameflow every student sees before they start. The three roles come into play during the planning and the audit; briefing, the board review and the debrief are worked as a single view. Materials arrive stage by stage: group structure and role cards at briefing, then the relief schedule, jurisdiction data and substance file for the build, then the information requests, comparable studies and press enquiry once the audit opens.
Students choose which reliefs, credits and jurisdictions to use, and see which of them lower the rate permanently and which only move tax between years.
Students decide where people, decisions and risk actually sit, because a structure is only worth the activity standing behind it when somebody asks.
Students reconcile the statutory rate to the effective one so a reader can follow it, and decide how much of the structure is explained before it is asked about.
Five stages. Students build a tax position from the statutory rate down, then an audit and a journalist test what stands behind it.
Briefing Docs · Group Structure · Role Cards
Briefing
Students watch the intro video, review a group with operations in four countries and take on all three roles, checking where the people are, where the profit is booked and the success criteria before any planning is done.
Relief Schedule · Jurisdiction Data · Substance File · Tool Tips
Plan & Substantiate
The position gets built. Working as planning, the student claims the research credit, sets intercompany prices and chooses where intellectual property is held; as substance, decides how many people and which decisions actually move; as reporting, writes the rate reconciliation. The position is submitted with an effective rate and a substance file behind it.
Information Requests · Comparable Studies · Press Enquiry · Live Scores
The Audit
Two years later the revenue authority opens an enquiry into the transfer pricing and the location of the intellectual property, and a journalist asks why a company with most of its customers in one country books most of its profit in another. The technical answer and the public answer are not the same, and both have to be given.
Board Questions · Position Record · Exposure Report · Review Pack
Board Review
Students are asked which steps survived the audit, how much of the saving was permanent, what the settlement and the provision cost against what the structure saved, and whether the position they signed would have been defended in public from the start.
Winners · Completion Summary
Debriefing
Students review their own position, compare effective rates across the cohort, revisit the audit outcomes that separated them and reflect on the feedback. Winners and the completion summary give you a structure for the discussion.
The student interface carries the structure, the substance and the reasoning. The professor panel carries the timeline, the controls and every individual position.
Students work step by step, with the points of rate each lever delivers, whether it is permanent and what substance it needs side by side, and a written reason required for every step above one point of rate.
The evidence column is the one that matters. The transfer pricing step saves 4.6 points of rate and is supported by three people and a board meeting held by video.
Your view. Adjust any stage timing, start or stop the session, and watch which students reported the lowest rate and what the audit took back.
Explore the student and professor experience, and discuss timing, setup and syllabus fit.
It works best as the session that turns tax from a calculation into a set of commitments.
An income statement and what a percentage of profit means. Effective rates, permanent differences, transfer pricing and deferred tax are explained inside the activity.
Mid to late module, typically weeks six to ten.
International tax frameworks and the minimum rate, deferred tax accounting, tax risk governance, business ethics, and any assessment asking students to evaluate a tax position.
The corporate tax course guide sets out where it sits in a full module.
The three mistakes students make on this case, and what each one gives you in the debrief. Our simulations are designed around them: read the learning science behind it.
1
A structure is not a transaction, it is a position that has to be held for several years against people who can ask questions. The lowest rate in the cohort is usually the one with the largest provision against it two years later.
2
Accelerating a deduction lowers this year's rate and raises a later one. Students who build a headline rate out of timing differences have borrowed from the future and reported it as performance, which the cash tax reconciliation exposes immediately.
3
A structure that books profit where nobody makes a decision fails on the first information request, whatever the documentation says. Deciding how many people actually move is the real choice, and it has a cost that the planning role would rather not pay.
The debrief runs itself. Every student sees their results, the cohort comparison and the decisions that produced them, with nothing for you to prepare. If you would rather lead the discussion, these questions work straight from a slide, and they use what your cohort actually did.
Assessment is optional. Run the simulation ungraded as an applied activity, or use platform data as supporting evidence. Every student generates a structure, a substance file, an effective rate reconciliation, audit responses and written rationales. Because the simulation is single-player, every input belongs to one named student, so there is no group-work marking to untangle. All of it exports as CSV or PDF, per student, so you can assess reasoning rather than a result.
On generative AI: written rationales are exactly what marking teams now worry about. Because every rationale here is tied to a structural choice the student made inside the platform, with the audit outcome sitting next to it, the reasoning can be checked against the evidence rather than taken on trust.
93% of students rate Finsimco simulations Excellent, across more than 30,000 responses.
Teaching notes, a setup and facilitation guide and a gameflow diagram come with it, and we support your first delivery directly.
Run it ungraded the first time. Assessment is optional and can be added once you have seen how your cohort responds.
Pause or stop at any point and resume later without losing submitted data, so an overrun costs you a timetable slot, not the activity.
Read what lecturers say.
Ron Tuninga, Managing Director for EMEA at AACSB, and Victor Hedenberg, Membership Director at AMBA, on why simulation-based learning belongs in business education. Watch both interviews.
If this one is not quite right for your module, these are the closest alternatives.
A one-page summary of this simulation, covering stages and timings, roles, concepts, learning outcomes and the debrief questions, plus a full sample teaching pack from one of our live simulations, so you can see exactly what you would be running.
During the call, we can:


